Insights into IFRS 15 – Determining the transaction price
Learn how to determine the transaction price under Step 3 of IFRS 15's five-step revenue recognition model, including key considerations for customer contracts and financial reporting.
01 Jan 2020 1 min read
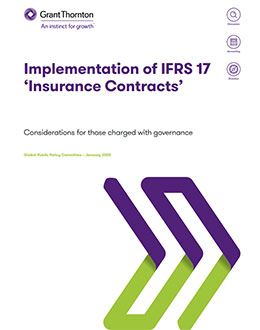
IFRS 17 heralds a new era of accounting for insurance contracts because it sets out principles-based requirements that aim to improve the comparability of the measurement and presentation of insurance contracts across entities reporting in jurisdictions applying International Financial Reporting Standards. The impact of IFRS 17 will be felt by many stakeholders, including, but not limited to: preparers of financial statements, those charged with the governance of entities that issue insurance contracts, investors, regulators, analysts and auditors.
Learn how to determine the transaction price under Step 3 of IFRS 15's five-step revenue recognition model, including key considerations for customer contracts and financial reporting.
Share-based payments have become increasingly popular over the years, with many entities using equity instruments or cash and other assets based on the value of equity instruments as a form of payment to directors, senior management, employees, and other suppliers of goods and services.
Share-based payment transactions with non-employees involve compensating parties other than employees, such as suppliers of goods and services.
Get the latest information in your inbox.
Subscribe to receive relevant and timely information and event invitations.